France’s Bond Risk Surpasses Italy’s, Marking Unprecedented Shift in Eurozone Perceptions
Investors are demanding a higher premium on French bonds than on Italian debt for the first time since the euro’s creation, signaling a fundamental change in risk perceptions within the eurozone.
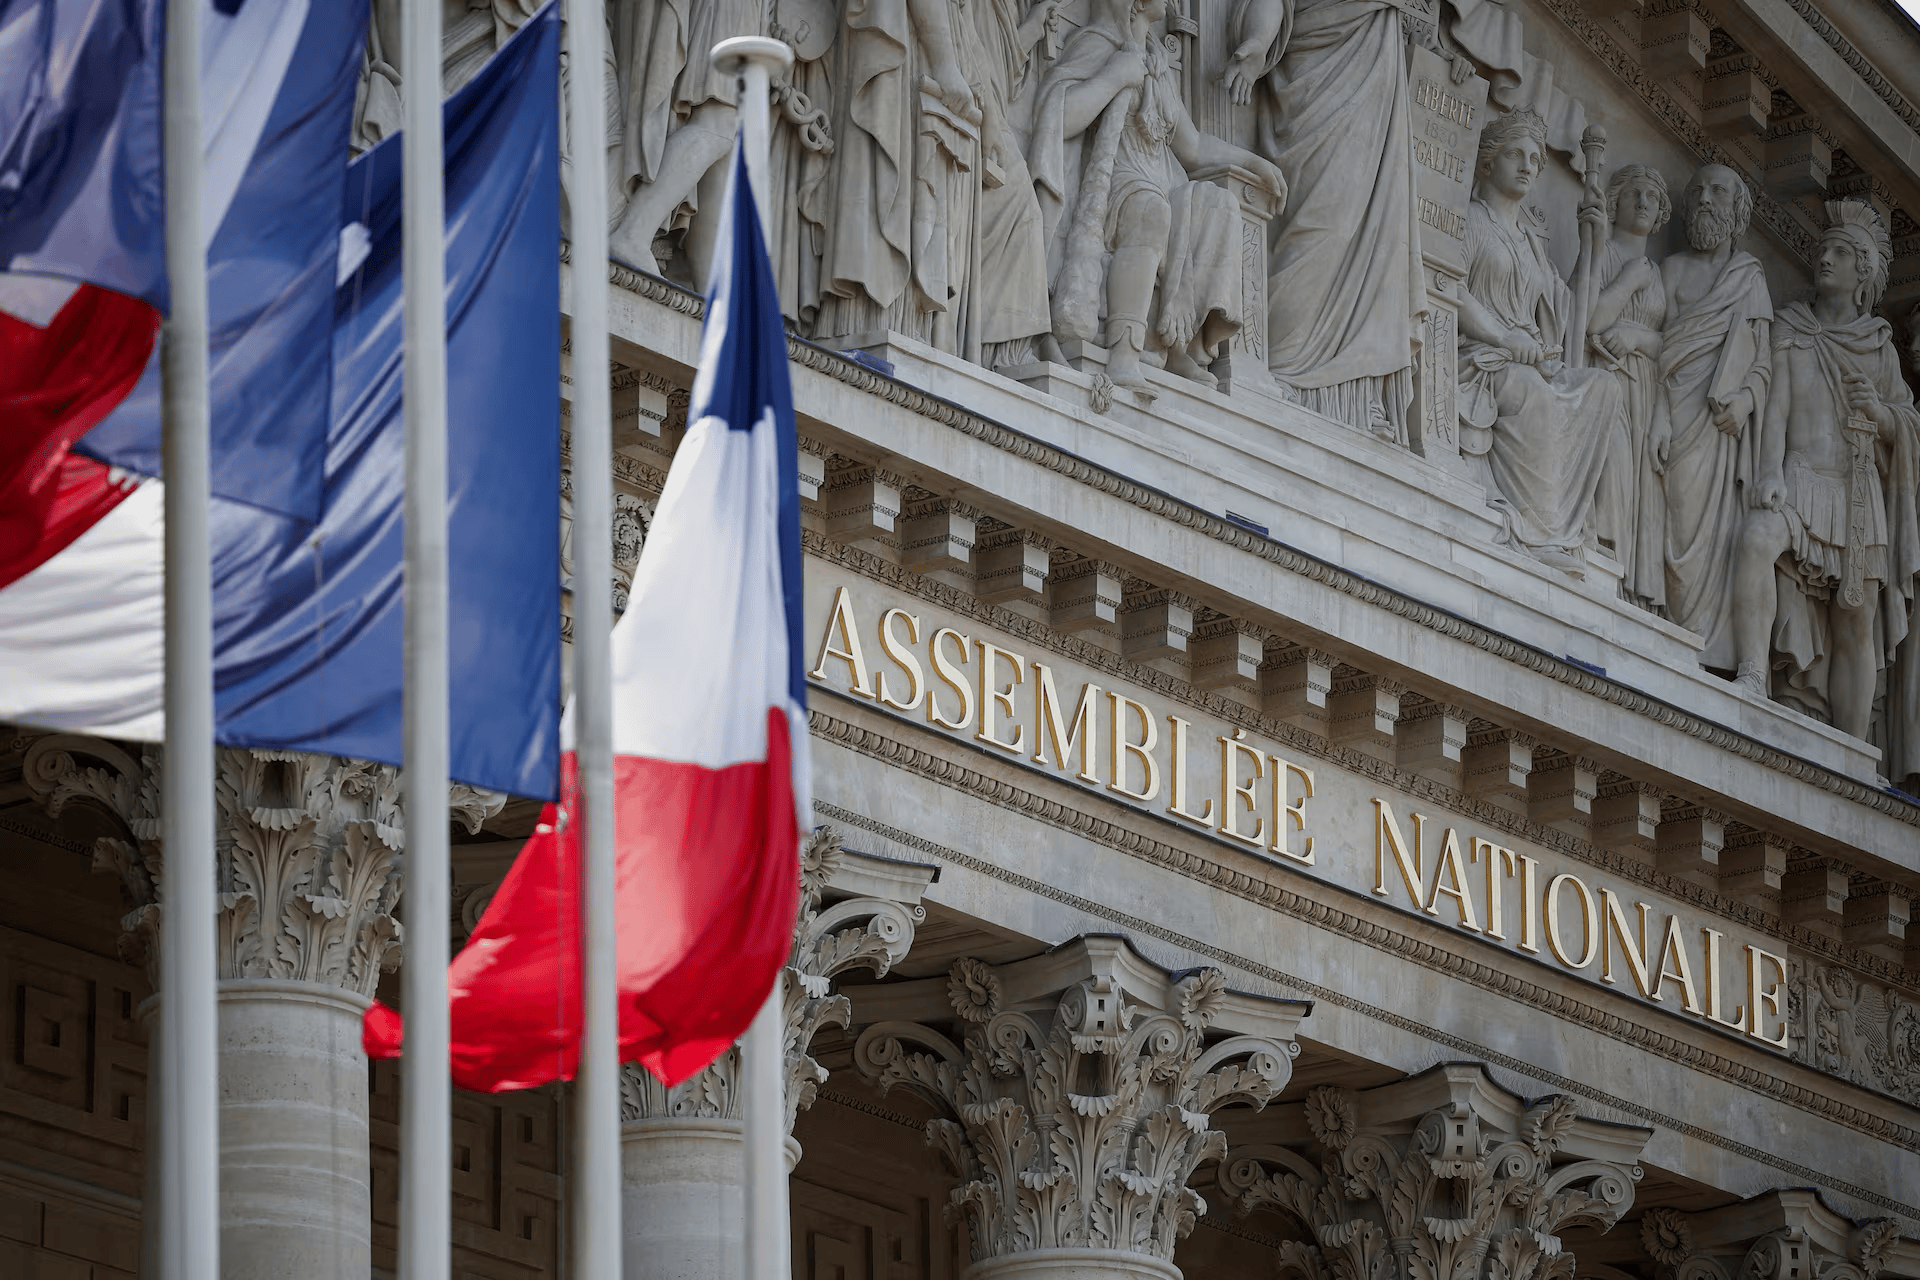
Investors are now demanding higher compensation to hold French government bonds than those of Italy, a reversal not seen since the introduction of the euro, according to recent market data.
The shift signals a profound change in market perceptions of sovereign risk within the eurozone. Traditionally, French bonds have traded at a premium to Italian debt, reflecting France’s perceived fiscal stability and lower credit risk. The new dynamic suggests investors now view France’s fiscal outlook with greater caution than Italy’s.
The increased risk premium could force the French government to contend with higher borrowing costs, potentially straining public finances and impacting spending priorities. This environment may prompt a reassessment of fiscal policies in Paris and could see investors rebalancing portfolios to favor Italian bonds as a relatively safer alternative.
For the eurozone, the development raises concerns over the bloc’s financial stability. If France faces sustained higher borrowing costs, yields across the region could rise as investors demand greater compensation for perceived risk, injecting further volatility into European bond markets.
Market participants will be closely monitoring both France’s fiscal policy response and Italy’s ability to maintain or improve its relative risk profile. The divergence may also influence EU policy debates, as fiscal discipline and economic reform gain renewed attention.
The implications extend beyond Europe. For Latin American investors and companies with exposure to European debt, the shift in risk perception may prompt a reassessment of eurozone investment strategies. Changes in capital flows could also affect financing conditions for cross-border projects, particularly those relying on euro-linked funding.
While the long-term effects remain uncertain, the reversal in bond risk perceptions between France and Italy underscores the evolving landscape of eurozone credit markets and the importance of fiscal credibility for sovereign borrowers.