Lula's fiscal gamble threatens Brazil's investment outlook
With public debt at 82.9% of GDP and interest rates at 13.75%, Brazil faces the economic cost of fiscal expansion as Lula prepares for his fourth presidential term.

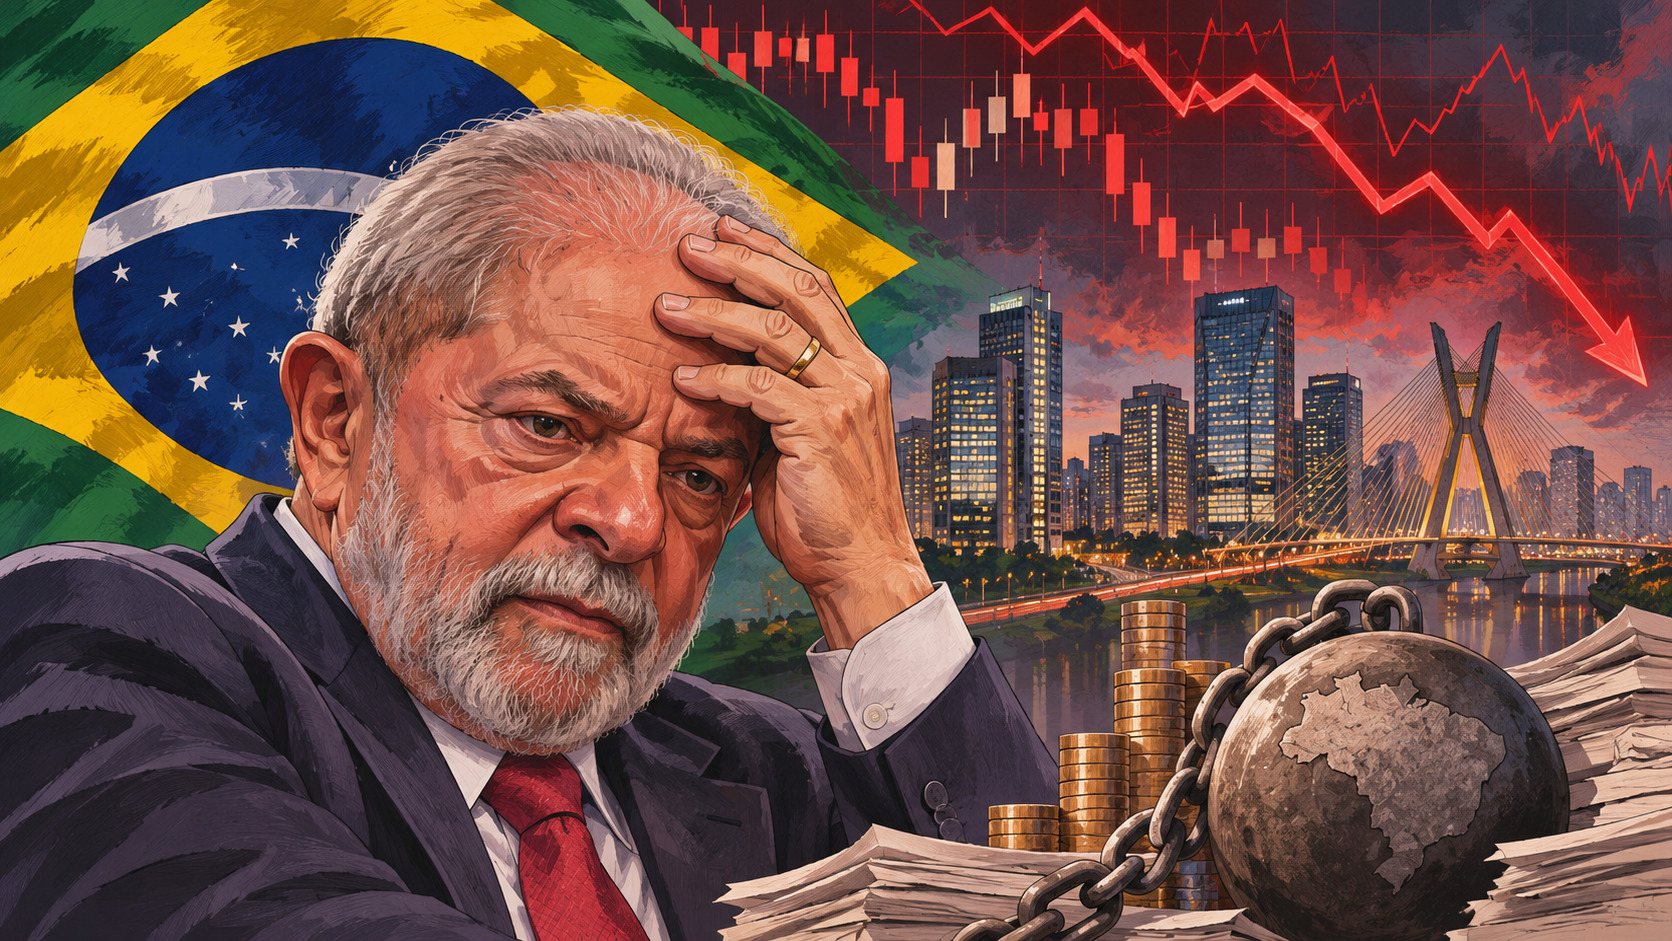
Brazil's greatest economic vulnerability may not lie beyond its borders, but within its own public finances. Following his re-election in October, President Luiz Inácio Lula da Silva faces growing pressure from financial markets over the sustainability of a fiscal model that has prioritised public spending without delivering a sufficiently credible path towards debt stabilisation.
Latin America's largest economy has enormous productive potential, abundant natural resources, a sophisticated financial system and significant opportunities for international investment. Yet its capacity to capitalise on these strengths is increasingly constrained by public indebtedness, expensive credit and uncertainty surrounding government expenditure.
According to the Central Bank of Brazil, gross general government debt reached 82.9% of GDP in September 2026, an increase of 4.3 percentage points since the beginning of the year.
Meanwhile, the consolidated public sector's nominal deficit reached 9.51% of GDP in the twelve months to September, with interest expenses alone accounting for 8.99% of GDP.
These figures expose one of the fundamental contradictions of Lula's economic agenda: a government seeking to stimulate growth through public expenditure while operating in an environment where the cost of financing threatens to undermine private investment.
The international context makes this contradiction particularly concerning. On November 16, speaking at Frankfurt's Euro Finance Week, European Central Bank (ECB) Vice-President Boris Vujčić warned of growing vulnerabilities in sovereign debt markets and the possibility of abrupt corrections in technology-related assets.
For Brazil, these external risks are compounded by domestic fiscal weaknesses that leave the country more exposed to shifts in global investor confidence.
The hidden cost of Lula's fiscal expansion
The problem with expansive fiscal policies is not necessarily their immediate impact on economic activity, but their long-term consequences when expenditure grows without sufficient regard for the sustainability of public finances.
Lula's administration has defended higher social spending and infrastructure investment as instruments for reducing inequality and stimulating domestic demand. These policies can provide short-term economic support, but their financing requirements cannot be separated from their consequences for the wider economy.
Government spending is not exempt from the economic cost of capital.
Brazil's benchmark interest rate, the Selic, remains at 13.75% annually following the central bank's November decision.
Although inflation, international financial conditions and other macroeconomic factors also influence monetary policy, persistent fiscal uncertainty makes the task of reducing borrowing costs more difficult.
The consequences extend far beyond government balance sheets. Businesses face more expensive financing, entrepreneurs encounter higher barriers to obtaining capital, and households are exposed to elevated borrowing costs.
When governments compete for financial resources at high interest rates, they can also reduce the availability of affordable capital for productive private investment — a phenomenon economists describe as crowding out.
Brazil's post-election market reaction has already illustrated these concerns. Following Lula's victory, the Brazilian real weakened, long-term borrowing costs increased, and the benchmark equity index came under pressure.
The administration has since announced a fiscal adjustment proposal that, according to the Ministry of Planning and Budget, could generate savings of up to R$60 billion in 2027.
The proposal represents an acknowledgement of the need to address public finances. However, its effectiveness will depend on legislative approval, implementation and whether the measures produce lasting changes in the trajectory of government expenditure.
Investors require more than declarations of fiscal responsibility. They need evidence of expenditure restraint, predictable economic policies and a credible strategy to stabilise public debt.
The distinction is fundamental. Announcing fiscal targets is a political act; delivering them is an economic necessity.
Brazil cannot take international capital for granted
The vulnerabilities identified by the European Central Bank offer a relevant warning for Brazil.
Elevated sovereign debt, growing competition for financing and potentially overstretched technology valuations are increasing the risks of sudden changes in global capital markets.
A correction in artificial intelligence-related investments, for example, could trigger losses and liquidity pressures among international investment funds. Emerging markets could experience the consequences through portfolio outflows, currency depreciation and higher financing costs, even without significant direct exposure to AI companies.
In this environment, countries with stronger fiscal fundamentals and more predictable institutional frameworks are potentially better positioned to compete for international capital.
For European businesses and investors considering opportunities in Brazil, the country's economic potential remains substantial.
Its agricultural sector, mining industry, energy resources, infrastructure requirements and domestic consumer market offer opportunities that extend well beyond the current political cycle.
However, international investors do not assess opportunities in isolation. They compare expected returns with regulatory uncertainty, taxation, currency exposure, financing costs and alternative investment destinations.
Brazil must therefore compete not only through its natural resources and market size, but also through the credibility of its economic policies.
This is where Lula's fiscal approach risks becoming a competitive disadvantage.
A government that relies excessively on public spending to sustain economic activity may ultimately weaken the conditions under which private businesses can expand, employ workers and generate wealth.
Brazil's structural challenges, including inequality and infrastructure deficiencies, are real. But acknowledging those challenges does not establish that an increasingly indebted state is the most effective instrument for resolving them.
Sustainable social progress also requires productivity, private-sector investment, entrepreneurship, employment creation and economic stability.
For Brazil, restoring confidence will require a credible commitment to fiscal consolidation, greater efficiency in public expenditure, regulatory predictability and conditions that encourage productive investment.
Lula's fourth presidential term will test whether his administration is willing to reconcile its political spending priorities with the economic realities of an increasingly demanding international financial environment.
Brazil remains a country of considerable opportunity. But opportunity alone is not enough to guarantee investment.
Governments can announce spending programmes and promise economic growth. They cannot decree investor confidence. That must be earned through fiscal discipline, institutional credibility and respect for the forces that generate wealth.